When debts are scattered across letters, apps, and phone calls, it is almost impossible to make good decisions. Which bill matters most? Which collector is waiting for a response? When does that validation period end? A debt tracker spreadsheet puts everything in one place so you can see the whole picture.
This guide shows you exactly which columns to include, how to use the tracker week to week, and how it connects to the rest of your debt remediation tools.
Key Takeaways
- List every debt, including those in collection, with balances, rates, minimums, status, and key dates.
- Track deadlines: validation periods, dispute response dates, court dates, and statute of limitations estimates.
- Use the tracker to prioritize payments by consequence, not by who calls most.
- Update it weekly; a tracker is only as good as its last update.
The Essential Columns
| Column | Why it matters |
|---|---|
| Debt name | Short label you will recognize |
| Original creditor | Needed to match collection accounts |
| Current collector/owner | Who you deal with now |
| Account/reference number | Matches letters and reports |
| Type | Secured, unsecured, medical, tax, student loan, judgment |
| Balance | Current amount claimed |
| Interest rate | For payoff strategy |
| Minimum payment | For budgeting |
| Status | Current, past due, collection, disputed, settled, judgment |
| Date of last payment | Key for statute of limitations |
| Date of first delinquency | Key for credit reporting period |
| SOL estimate | From your statute of limitations worksheet |
| Validation period ends | Deadline for disputing with collector |
| Dispute sent (date, method) | Proof of your actions |
| Response due/received | Tracks follow-up |
| On credit report? (EQ/EX/TU) | Shows which bureaus report it |
| Lawsuit? Court date? | Highest priority deadlines |
| Priority (1–5) | Your action order |
| Notes / next step | What to do and when |
How to Build It
- Create the columns above in any spreadsheet program.
- Gather your sources: credit reports, statements, collection letters, court papers.
- Enter one row per debt. If two collectors claim the same debt, enter both and note the duplication.
- Color-code status: for example, red for lawsuits, orange for open validation periods, green for resolved.
- Add a deadline view: sort by the nearest date in any deadline column.
- Total your balances and minimums at the bottom.
Sample Rows
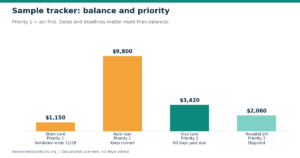
| Debt | Collector | Balance | Status | Last payment | Validation ends | Priority | Next step |
|---|---|---|---|---|---|---|---|
| Visa card | Bank (original) | $3,420 | Past due 60 days | 08/2026 | N/A | 2 | Call about hardship program |
| Store card | ABC Recovery | $1,150 | Collection | 03/2019 | 11/28/2026 | 1 | Send validation letter by 11/20 |
| Hospital bill | XYZ Collections | $2,060 | Collection, disputed | Never | Ended | 3 | Await itemized bill; apply for financial assistance |
| Auto loan | Credit union | $9,800 | Current | 10/2026 | N/A | 1 | Keep current |
Using the Tracker Week to Week
- Every Monday: Sort by deadlines and handle anything due in the next 14 days.
- When mail arrives: Update the relevant row and file the document. See organize debt documents.
- After every call: Update notes and your call log.
- Monthly: Update balances and check credit reports for changes.
Prioritizing With the Tracker
Use the priority column to rank actions by consequence:
- Lawsuits and court dates
- Housing, utilities, and essential secured debts
- Open validation periods
- Taxes, child support, and federal student loans
- Unsecured debts and verified collections
- Old or disputed collections (verify first)
For a deeper guide, read how to build a debt payoff plan, then connect your tracker to the debt payoff budget template.
Common Tracker Mistakes
- Leaving out debts you would rather not think about
- Recording a collector’s balance without verifying it
- Ignoring dates, which are often more important than balances
- Letting the tracker go stale for months
Example: The Deadline That Was Almost Missed
A hypothetical consumer builds his tracker over a weekend. Sorting by deadline, he discovers that a validation period ends in six days for a collection account he planned to “deal with later.” He sends a validation letter the next morning by certified mail.
The tracker also reveals that his two largest credit cards have the highest interest rates, and that one hospital bill is listed twice by two different collectors. He disputes the duplicate, requests the hospital’s financial assistance application, and targets extra payments at the highest-rate card. For the first time, his debt feels like a plan instead of a pile.
Where This Tracker Fits in Your Workflow
- Before: Pull your free weekly credit reports and gather all letters and statements.
- Alongside: Link each row to a folder in your document system and to your call log.
- After: Feed totals into your budget template and pick a payoff method with our free debt payoff calculator and with snowball vs. avalanche.
Quick-Use Checklist
- ☐ Every debt entered, including disputed ones
- ☐ Original creditor and current collector recorded
- ☐ Last payment and first delinquency dates added
- ☐ All deadlines entered and sorted
- ☐ Priority assigned to each debt
- ☐ Weekly update day chosen
Frequently Asked Questions
Yes. Including every debt gives you an accurate picture of your total obligations and budget.
Keep the original row and add the new collector, noting the date and source of the change.
Yes. A complete tracker makes consultations with credit counselors, attorneys, or our team faster and more productive.
Yes, but a spreadsheet makes sorting by deadline and totaling balances much easier.
Get Organized Today
Debt Remediation Tools from Foxboro Consulting Group, Inc. includes a ready-made debt tracker with built-in deadline sorting and status color-coding, designed to work with our letters and worksheets.
Overwhelmed by statements and letters? Build your tracker this week and see your whole picture.
Disclaimer: Templates and tools in this article are provided for general educational purposes and are not legal advice. Adapt every letter to your own facts, keep copies of everything you send, and consult a licensed attorney in your state before responding to a lawsuit or court deadline.