Key takeaways
- A debt inventory is a complete list of everything you owe, with balances, interest rates, minimum payments, due dates and status.
- Most people are surprised by at least one number when they write everything down. That clarity is the foundation of every payoff plan.
- Use your credit reports, recent statements and any collection letters to make sure nothing is missing.
- Your inventory lets you calculate your total debt, total minimum payments, weighted average interest rate and debt-to-income ratio.
- Flag debts that are in collections, old, or unfamiliar. They may need validation before you pay.
Debt has a way of feeling bigger and scarier when it’s scattered across apps, envelopes and inboxes. One card’s due date sneaks up. A medical bill gets buried. A collection letter arrives for something you don’t remember.
The single most useful thing you can do before choosing a payoff strategy is to put every debt on one page. This guide shows you exactly what to include, how to gather the information, and how to use your inventory to make decisions.
Step 1: Gather your information
Collect:
- your free credit reports from Equifax, Experian and TransUnion at AnnualCreditReport.com
- the most recent statement for each account
- your online banking and loan portals
- any collection letters or court papers
- notes on debts that may not appear on credit reports, such as money owed to family, medical payment plans, tax balances or buy-now-pay-later plans
Step 2: Set up your worksheet columns
Here’s what to include for each debt:
| Column | Why it matters |
|---|---|
| Creditor (original lender) | Who you originally owed |
| Current holder / collector | Who’s collecting now, if different |
| Account (last 4 digits) | Identification without exposing full numbers |
| Type | Credit card, auto, student, medical, personal, tax, etc. |
| Secured or unsecured | Secured debts are tied to collateral (car, house) |
| Current balance | What you owe today |
| Interest rate (APR) | Drives the cost of carrying the debt |
| Promo rate and end date | Note when 0% or low rates expire |
| Minimum payment | Required monthly amount |
| Due date | Avoid late fees |
| Status | Current, late, charged off, in collections, judgment |
| Date of first delinquency | Matters for credit reporting and statute of limitations |
| Contact information | Phone, address, website |
| Notes | Hardship programs, disputes, promised settlements |
Never write full account numbers, Social Security numbers or passwords on your worksheet.
Step 3: Fill it in
Example inventory:
| Debt | Type | Balance | APR | Minimum | Due | Status |
|---|---|---|---|---|---|---|
| Store card | Credit card | $1,200 | 24.99% | $35 | 5th | Current |
| Visa | Credit card | $4,800 | 19.99% | $120 | 18th | Current |
| Personal loan | Installment | $7,500 | 11.50% | $250 | 1st | Current |
| Hospital bill | Medical plan | $900 | 0% | $50 | 22nd | Current |
| Old gym membership | Collection | $640 | n/a | n/a | n/a | In collections (validate first) |
| Total (current debts) | $14,400 | $455 |
Step 4: Calculate your key numbers
Total debt
Add all balances. In the example, current debts total $14,400, plus a $640 collection account to investigate.
Total minimum payments
$455 per month on current debts. This is the floor your budget must cover.
Weighted average interest rate
A simple average of rates is misleading because larger balances matter more. Use:
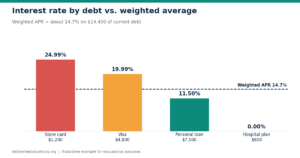
Weighted APR = Σ (Balance × APR) ÷ Total balance
| Debt | Balance × APR |
|---|---|
| Store card | $1,200 × 24.99% = $299.88 |
| Visa | $4,800 × 19.99% = $959.52 |
| Personal loan | $7,500 × 11.50% = $862.50 |
| Hospital bill | $900 × 0% = $0.00 |
| Total | $2,121.90 |
Weighted APR = $2,121.90 ÷ $14,400 = about 14.7%
That means these debts are costing roughly $2,122 a year, or about $177 a month, in interest at current balances. That’s a powerful number to keep in mind when you’re deciding whether a consolidation loan or balance transfer would help.
Debt-to-income ratio
Divide total monthly debt payments (including housing) by your gross monthly income. See our debt-to-income ratio guide or use our free debt-to-income calculator.
Step 5: Sort your list
Sort the worksheet two ways:
- By balance (smallest to largest) for the debt snowball
- By APR (highest to lowest) for the debt avalanche
Then compare the two plans. Our snowball vs. avalanche example uses these same debts. To see your own debt-free date, try our free debt payoff calculator.
Step 6: Flag debts that need special handling
Debts in collections
Before paying a collector:
- confirm the debt is yours and the amount is correct
- confirm who owns the debt now
- check whether it’s past your state’s statute of limitations
- request validation in writing if you’re within the dispute window
Our sister site, Debt Remediation, explains time-barred debt and debt validation letters. Track every letter and call with our collection correspondence log.
Promotional rates
Note when promotional rates end. A balance at 0% today might jump to 25% in four months, which could change your payoff priority.
Secured debts
Missing payments on secured debts can mean losing the collateral, such as a car. Keep these current even while focusing extra money elsewhere.
Tax debts and court judgments
These may carry special collection powers. Prioritize staying in compliance and seek professional advice.
Step 7: Update it monthly
Your inventory is a living document. Each month:
- update balances
- check off paid-off debts (and celebrate)
- note any rate changes or new debts
- recalculate your total and weighted APR
Watching your total debt fall is one of the most motivating parts of the process.
Spreadsheet tips
If you build your own spreadsheet:
- use SUM for total balances and minimums
- use SUMPRODUCT(balances, rates) / SUM(balances) for weighted APR
- use conditional formatting to highlight upcoming due dates or promo expirations
- keep a tab for each month to track progress over time
Frequently asked questions
Include it for a complete picture and for DTI calculations, but most people exclude it from snowball or avalanche payoff plans.
Check your latest statement, log into the account, or call the creditor. For collection accounts, interest may or may not be accruing.
Include it anyway. Not all creditors report, and some debts, like personal loans from family, never appear.
At least a few times a year, and before major financial decisions. Free weekly reports are available at AnnualCreditReport.com.
Download the worksheet
Get our free debt inventory worksheet and fill it in tonight. Then pair it with our budget for debt payoff guide to build your plan.
This article is for general educational purposes and is not financial or legal advice.
1 Comment
Debt Collection Call Log Template: Track Calls & Letters
[…] debt inventory worksheet lists every debt. Your correspondence log tracks what’s happening with each one. Together, they […]