
You cannot pay off debt with money you do not have. Before choosing a payoff strategy or making settlement offers, you need an honest picture of what comes in, what must go out, and what is truly available for debt. A debt payoff budget template gives you that picture.
This guide uses a zero-based approach, where every dollar is assigned a job, and shows how to protect essentials while finding money for debt.
Key Takeaways
- Start with take-home income and essential expenses; debt payments come from what remains.
- Zero-based budgeting assigns every dollar to a category so nothing disappears.
- Small cuts across many categories often add up to meaningful debt payments.
- Revisit the budget monthly and adjust for irregular income and seasonal expenses.
The Template
MONTHLY DEBT PAYOFF BUDGET – [MONTH YEAR]
INCOME (take-home)
Paycheck 1: $______ Paycheck 2: $______
Other income (benefits, side work, support): $______
TOTAL INCOME: $______
ESSENTIALS (pay first)
Rent/mortgage: $______
Utilities (electric, heat, water): $______
Phone/internet: $______
Groceries: $______
Transportation (gas, transit, insurance): $______
Insurance (health, renters/home, life): $______
Medications/medical: $______
Child care/child support: $______
TOTAL ESSENTIALS: $______
SECURED AND PRIORITY DEBTS
Car loan: $______
Tax payment plan: $______
Other secured: $______
TOTAL PRIORITY DEBTS: $______
SAVINGS
Emergency fund (even $25 helps): $______
FLEXIBLE SPENDING
Household, clothing, personal care: $______
Subscriptions: $______
Dining out/entertainment: $______
Gifts/holidays (monthly set-aside): $______
TOTAL FLEXIBLE: $______
AVAILABLE FOR UNSECURED DEBT
Total income – essentials – priority debts – savings – flexible = $______
UNSECURED DEBT PAYMENTS
Minimums: $______
Extra payment (target debt): $______
Settlement savings: $______
TOTAL UNSECURED: $______
LEFTOVER (should equal $0): $______
How to Fill It In
- Use take-home pay, not gross income.
- Look at the last three months of bank and card statements to find real spending, not guesses.
- Include irregular expenses by dividing annual costs, such as car registration or holidays, by 12.
- Protect essentials first. Housing, utilities, food, transportation to work, and insurance come before unsecured debt.
- Assign every remaining dollar until leftover equals zero.
Where to Find Extra Money
| Area | Ideas |
|---|---|
| Subscriptions | Cancel unused streaming, apps, and memberships |
| Phone and internet | Ask for retention discounts or switch to lower-cost plans |
| Insurance | Shop for quotes annually; raise deductibles if you have savings |
| Groceries | Meal plan, buy store brands, reduce takeout |
| Utilities | Ask about budget billing or assistance programs |
| Income | Overtime, side work, selling unused items |
| Medical | Apply for financial assistance programs for medical bills |
Even $150 a month in savings across several categories can pay off a small debt within months.
When the Numbers Do Not Work
If essentials and minimum payments exceed your income:
- Contact creditors about hardship programs
- Prioritize essentials and secured debts
- Verify collection accounts before paying them
- Consider a nonprofit credit counseling agency
- Explore settlement or bankruptcy options with professional advice
Read how to build a debt payoff plan for prioritization guidance.
Connecting the Budget to Your Payoff Strategy
Once you know your available amount, choose a strategy:
- Snowball: Extra payment goes to the smallest balance first
- Avalanche: Extra payment goes to the highest interest rate first
See debt snowball vs. avalanche for a side-by-side example, and record your plan in the debt tracker spreadsheet.
Irregular Income Tips
If your income varies:
- Budget based on your lowest typical month
- Put extra income in a holding account
- Use the holding account to cover low months first, then send the surplus to debt
Example: Finding $310 a Month
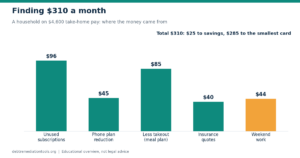
A hypothetical household with $4,600 in monthly take-home pay believes there is nothing left for debt beyond minimums. Using the template and three months of statements, they find $96 in unused subscriptions, a $45 phone plan reduction, $85 less on takeout by meal planning, and a $40 insurance savings after shopping quotes. They also add $44 a month from occasional weekend work.
That is $310 a month. They put $25 into an emergency fund and $285 toward their smallest credit card balance, paying it off in six months, then roll that payment to the next card.
Where This Budget Fits in Your Workflow
- Before: List every debt in the debt tracker so minimums and priorities are clear.
- Alongside: Use the debt-to-income ratio calculator to measure your overall debt load.
- After: Direct your available amount using snowball or avalanche, and set aside settlement savings for verified debts.
- If the numbers do not work: Send a hardship letter to creditors and consider professional help.
Quick-Use Checklist
- ☐ Take-home income from real pay stubs
- ☐ Three months of actual spending reviewed
- ☐ Annual expenses divided by 12
- ☐ Essentials and secured debts funded first
- ☐ Small emergency fund included
- ☐ Leftover equals zero
Frequently Asked Questions
You are spending more than you earn. Start with the largest flexible categories, contact creditors about hardship options, and consider professional help.
A small emergency fund helps prevent new debt when unexpected expenses arise. Many people start with a modest target.
Monthly, and whenever income or expenses change significantly.
Yes. If you plan to settle debts, set aside savings in a separate account so you can make lump-sum offers.
Make Your Money Work for You
Debt Remediation Tools from Foxboro Consulting Group, Inc. includes this budget template in printable and spreadsheet form, connected to our tracker and payoff calculators.
Ready to find money for debt? Fill in this month’s budget using last month’s real numbers.
Disclaimer: Templates and tools in this article are provided for general educational purposes and are not legal advice. Adapt every letter to your own facts, keep copies of everything you send, and consult a licensed attorney in your state before responding to a lawsuit or court deadline.